The Complete Guide to Investment Management RFPs (2026)
TL;DR for fund managers
- An investment management RFP is a formal, scored questionnaire an allocator uses to pick a manager for a defined mandate. Win rates rise when you bid selectively.
- Endowments and foundations typically send an RFP to 5–10 firms, interview 2–3 finalists and allow 3–4 weeks to respond (Fidelity).
- Public pensions often screen managers through consultant databases (such as CallanDNA and Wilshire Compass) before a single RFP is read (NYC Comptroller).
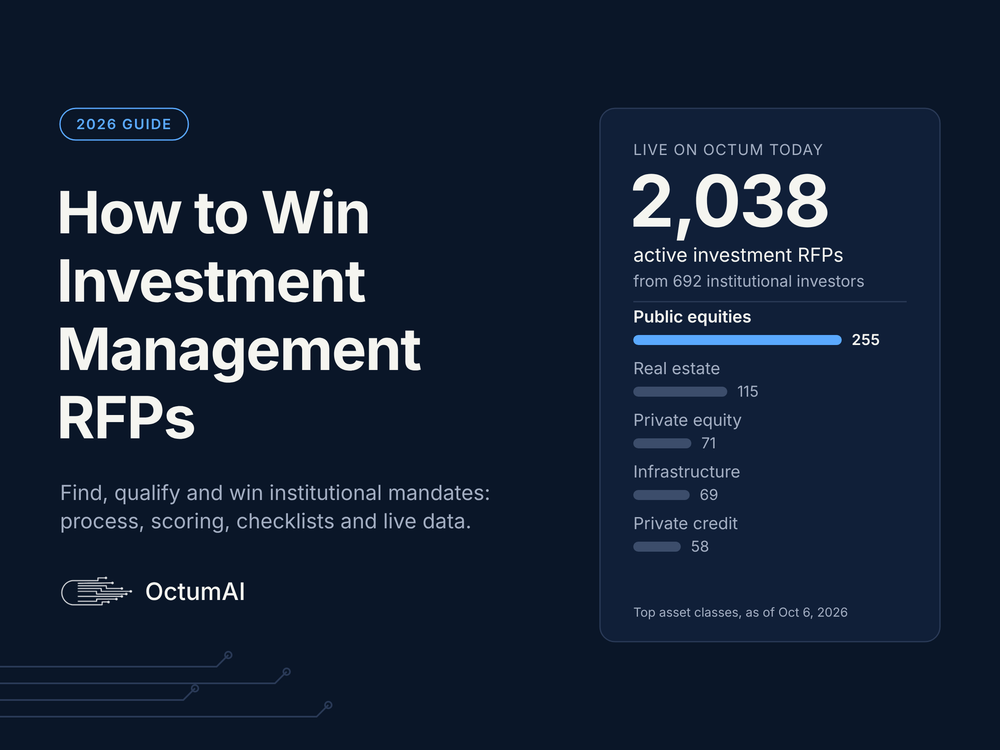
- Octum tracked 2,038 active investment RFPs from 692 institutional investors as of October 6, 2026 (octum.ai).
- Most lost RFPs are lost before writing starts: wrong mandate, missed minimums, stale database profile or no relationship with the consultant.
What is an investment management RFP?
An investment management RFP (request for proposal) is a formal, standardized questionnaire that an institutional investor sends to asset managers to compare them on the same terms and hire one for a defined mandate. It is a mechanism that institutions (asset owners) use to gather information, evaluate options and select an asset manager to manage their funds.
For the people who answer them, RFPs are not paperwork. They are the front door to institutional assets (think – endowments, foundations, pensions, sovereign wealth funds, government funds). A single public pension mandate can be worth hundreds of millions of dollars. The RFP is how you get in the room.
The workload keeps growing. In a Cerulli Associates survey reported by Institutional Investor, 91% of asset managers said their teams struggled to meet RFP and DDQ deadlines. RFP volume rose about 13% from 2017 to 2018, DDQs rose about 20%, and managers had doubled their RFP teams over three years.
This guide is written for RFP writers, proposal managers, investor relations staff and business development leads at fund managers. It covers:
- The vocabulary: RFP, RFI, RFQ, DDQ and consultant databases
- Who issues investment RFPs and how a manager search runs
- What the questionnaire asks, section by section
- Where to find RFPs before your competitors do
- How to decide whether to bid
- How to write, review and submit a winning response
- How allocators score you, and the mistakes that sink proposals
Other names you will see. Investment RFPs go by many labels. Search for all of them: investment management RFP, RFI (request for information), asset management RFP, investment advisor RFP, investment consultant RFP, OCIO RFP, notice of search, manager search, request for qualifications (RFQ) and due diligence questionnaire (DDQ). The content overlaps heavily, whatever the label.
RFP vs. RFI vs. RFQ vs. DDQ: what each document is for
Each document sits at a different stage of the search, and each deserves a different level of effort. The table shows what to expect from each.
| Document | Stage | Typical length | What it decides | How much effort to invest |
|---|---|---|---|---|
| RFI (request for information) | Pre-screen | About 10–20 high-level questions, often capped at 10 pages (Commonfund) | Who gets invited to the RFP | Medium: short, but it gates everything after it |
| RFP (request for proposal) | Formal evaluation | About 50 questions and 25 pages of answers, plus bios, ADV and sample reports (Commonfund) | Who becomes a finalist | High: this is the scored document |
| RFQ / notice of search | Public procurement | Varies; minimum requirements are pass/fail | Who is eligible at all | Check minimums first, then treat like an RFP |
| DDQ (due diligence questionnaire) | Deep diligence or annual monitoring | Long; templated by industry bodies | Whether the allocator can approve or keep you | High, but highly reusable |
| Consultant database profile | Always on | Structured data fields and narratives | Whether you appear in the consultant’s screen | Ongoing: update quarterly |
Three standard DDQ templates are worth keeping current answers for:
- ILPA DDQ 2.0 for private equity and private markets. ILPA released it in November 2021 to standardize the most frequent diligence questions LPs ask GPs (user guide).
- AIMA Illustrative DDQ for hedge fund, private credit and private equity managers. AIMA’s first DDQ dates to 1997; the 2017 edition added private credit and private equity coverage.
- PRI LP Private Equity Responsible Investment DDQ, which forms the ESG section of the ILPA DDQ.
The practical takeaway: an RFP is usually the second document you see, not the first. Firms that win treat the RFI and the database profile as part of the RFP.
Who issues investment RFPs (and who really decides)
Investment RFPs come from asset owners with fiduciary duties, and those duties shape every question they ask. Knowing the issuer type tells you how formal the process will be, who reads your answers and which rules apply to you.
| Issuer | Typical searches | How formal | What to know |
|---|---|---|---|
| Public pension plans (state, county, city) | Public and private markets managers, consultants, custodians | Very: procurement law, public posting, open records | Often require consultant database entry; pay-to-play rules apply |
| Corporate DB and DC plans (401(k), 403(b)) | Managers, OCIO, recordkeepers, target-date and stable value | High: ERISA fiduciary process | Committees must document a prudent process |
| Endowments and foundations | OCIO, investment advisor, specialist managers | Medium: invitation-only is common | Mission, spending policy and governance fit matter |
| Insurance companies | Fixed income, private credit, insurance-dedicated mandates | High | Capital treatment and reporting needs drive questions |
| Sovereign wealth funds and central banks | Large segregated mandates, co-investment, private markets | High, often private | Relationships and capacity at scale |
| Taft-Hartley and multiemployer plans | Managers and consultants | High | Trustees from labor and management both vote |
| Hospitals, municipalities, authorities | Investment advisors, cash and fixed income managers | High: public procurement | Short-duration and liquidity mandates are common |
The people behind the RFP. A plan sponsor or staff member runs the process, answers your questions and collects responses. An investment committee, usually an odd number of members such as three, five or seven, scores and votes. Fidelity recommends a core sub-committee of three to five people to keep reviews moving (Fidelity).
The consultant is the gatekeeper. Most large plans hire an investment consultant to design the search, screen the universe and recommend finalists. Common pension consultants in the U.S. include Meketa, Wilshire, NEPC, Asset Consulting Group, and Aon. There are also specialist consultants that can focus on a specific asset class like real assets, hedge funds, or private equity. Some common names include Cambridge Associates, Hamilton Lane, StepStone, and Aksia. Many consultants screen fund managers in their own proprietary databases or commercial databases before any RFP is issued, and public plans often make database entry a condition of being considered. If your data is missing or stale, you are invisible to the search. Increasingly, global asset owners are using platforms like Octum to conduct diligence as well, so providing Octum with manager data could help increase your presence.
Why they issue RFPs at all. RFPs create a documented, apples-to-apples comparison that protects fiduciaries. The U.S. Department of Labor notes that documenting the decision process is one way fiduciaries show they acted prudently (DOL). Common triggers include:
- A scheduled review. Octum researchers suggests organizations above $10 million in assets run a formal RFP every four years; Fidelity suggests a five- to seven-year cycle for nonprofits.
- An asset allocation change that creates a new mandate (for example, a new private credit or infrastructure target).
- Manager underperformance, a watch-list placement or a team departure.
- A contract expiration that public procurement rules require them to rebid.
- A move to an outsourced CIO (OCIO) model.
The investment manager search, stage by stage
A manager search narrows from a broad universe to one hire, and the biggest cut happens before the RFP is written. Fidelity reports that nonprofits typically send an RFP to 5–10 firms, allow three to four weeks to respond and interview two or three finalists. Commonfund suggests an RFI to ten or more firms first, then limiting the RFP to about five.
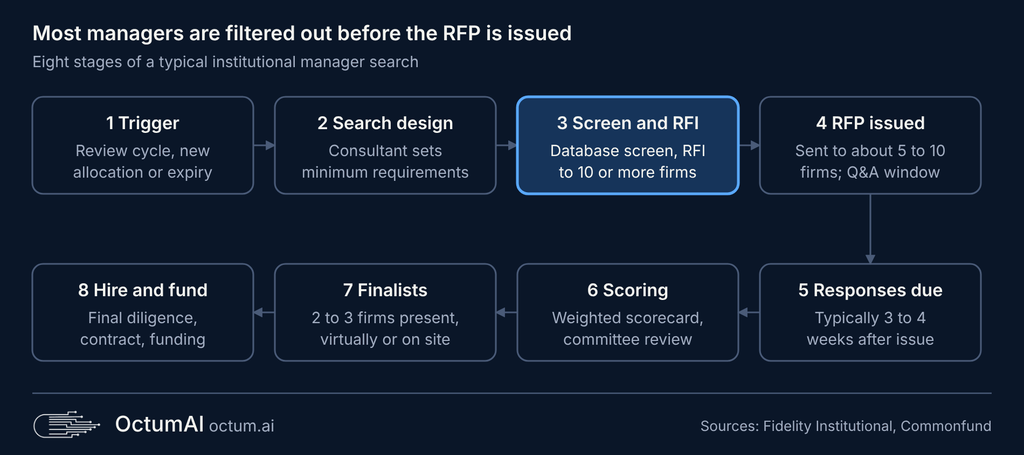
What each stage means for your business development team:
| Stage | What the allocator is doing | What you should be doing |
|---|---|---|
| 1. Trigger | Scheduled review, asset allocation change, underperformance, contract expiry | Track board minutes, asset allocation studies and watch lists; know the trigger before the RFP |
| 2. Search design | Consultant drafts criteria, minimums and the evaluation rubric | Stay on the consultant’s radar with research meetings and updated data |
| 3. Screen and RFI | Database screen or RFI to a broad group | Keep database profiles complete; answer RFIs fast and on-message |
| 4. RFP issued | Questionnaire sent or posted; Q&A window opens | Run go/no-go within 48 hours; submit clarifying questions |
| 5. Responses due | Responses collected | Submit early; confirm receipt; respect the quiet period |
| 6. Scoring | Committee scores against weighted criteria | Make answers easy to score; nothing to do but wait |
| 7. Finalists | 2–3 firms present | Bring the PM; answer the scorecard; rehearse hard questions |
| 8. Hire and fund | Final diligence, contract, funding | Prepare legal and operational onboarding in advance |
Public plans work differently. Many public pensions post searches openly and require database entry. The New York City Comptroller’s searches, for example, ask firms to enter their information in each investment consultant’s database, such as CallanDNA or Wilshire Compass, and consultants then report which firms meet the minimum requirements (NYC City Record). CalPERS also runs an always-open portal for unsolicited investment proposals, alongside targeted solicitations.
A live example: Indiana’s global equity search
The Indiana Public Retirement System (INPRS), which manages about $61 billion, shows how a public search runs. Its RFP 26-05 for Global Public Equity Management sets out every stage in advance:
| Milestone | Date |
|---|---|
| RFP released | September 18, 2026 |
| Questions due | October 9, 2026 |
| Answers published | October 16, 2026 |
| Proposals due | October 30, 2026, 3:00 p.m. EDT |
| Finalist presentations | December 2026 |
| On-site visits | January–February 2027 |
| Manager selection | March 2027 |
| Contract negotiation | April–May 2027 |
Three details are worth noticing. The minimums are pass/fail: for the active long-only option, at least $10 billion in firm institutional AUM, a seven-year track record and a GIPS-compliant record of at least seven years. Responses go through an online RFP portal only, and late submissions are not considered. A missing itemized fee proposal eliminates the respondent outright. From release to selection, the search takes about six months.
Anatomy of an investment RFP: what allocators ask
Nearly every investment RFP asks about the same eight areas, wrapped in the issuer’s own background, timeline and submission rules. If your content library has a current, approved answer for each, you are most of the way to a response before the RFP arrives.
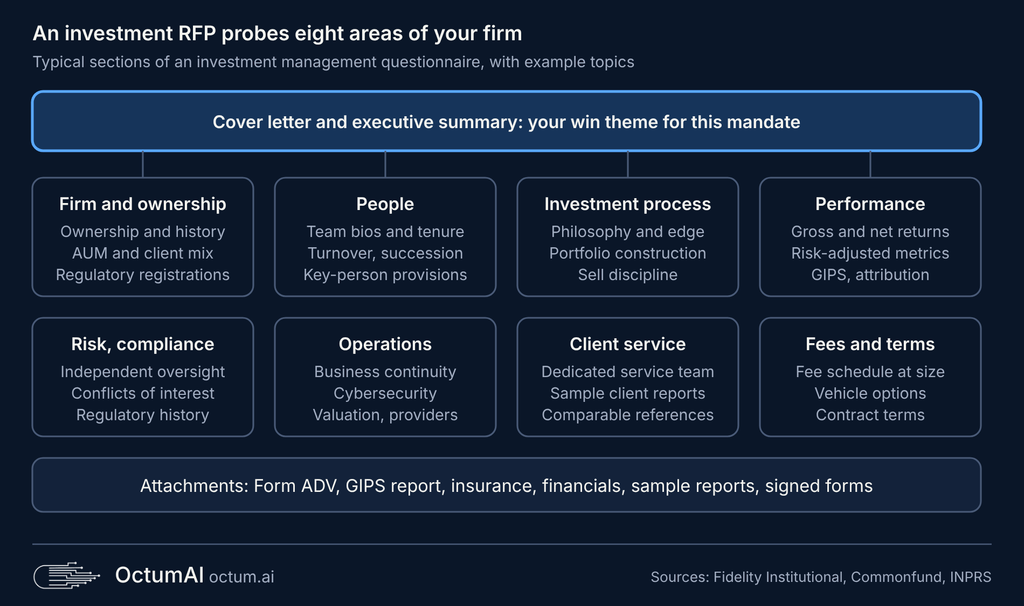
The issuer’s half of the document. Before the questions, expect an introduction to the organization, the scope and size of the mandate, minimum qualifications, evaluation criteria, the timeline (question deadline, due date, selection date) and submission format rules.
Questions that carry the most weight. Fidelity tells allocators to ask for organizational history and mission, team structure and stability, investment philosophy and process, performance and attribution, the client service model, fee structure and transparency, and experience with similar clients. It also stresses identifying and managing conflicts of interest (Fidelity).
Check-the-box items. Commonfund lists standard diligence items such as attaching your Form ADV, describing your disaster recovery plan and disclosing any criminal or regulatory history (Commonfund). These rarely win a search, but missing one can lose it. Keep your Form ADV current, because evaluators will pull it.
Typical length. Commonfund estimates a typical RFP at about 50 questions, roughly 25 pages of answers, plus around 50 pages of bios, ADV and sample reports. Ask for, and respect, page limits.
Want real examples? Start with a live search: INPRS RFP 26-05 for Global Public Equity Management, listed on the INPRS procurement page. Its evaluation criteria run from background and investment team through strategy, performance, risk management, fees, trading and operations, compliance and client service, which maps closely to the eight areas above. For older public examples, read RFPs from the State of Delaware, the New Jersey Turnpike Authority and NYC BERS.
Where to find investment RFPs
Investment RFPs are scattered across hundreds of procurement portals, consultant processes and private networks, so the managers who see the most opportunities are the ones who monitor the most channels. No single channel shows everything.
| Channel | What you find there | Strengths | Gaps |
|---|---|---|---|
| Public pension and municipal portals | Formal RFPs, RFQs and notices of search, e.g. INPRS procurement, the NYC Comptroller’s notices of search and CalPERS bid opportunities | Official documents and dates | Hundreds of sites; formats differ; easy to miss |
| Board agendas and minutes | Asset allocation changes, watch lists, planned searches | Earliest warning, months ahead | Time-consuming to read |
| Consultant databases | Searches run by consultants on their clients’ behalf | Required for many public searches | You see the screen only if you are in it |
| Trade press | Searches and hires reported by outlets such as FIN News and Institutional Investor | Context and competitor intelligence | Often reported after the RFP is out |
| Direct relationships | Invitation-only RFPs from endowments, foundations and family offices | Highest win rates | Limited to who you already know |
| RFP trackers and investor intelligence | Aggregated active RFPs plus the investors and people behind them, e.g. Octum | One feed across asset classes and issuers | Still needs your judgment on fit |
What the market looks like right now. As of October 6, 2026, Octum tracked 2,038 active RFPs from 692 institutional investors. Of the 766 RFPs classified by asset class, public equities led, followed by real estate. Private markets (private equity, infrastructure and private credit) together outnumbered fixed income and hedge funds combined.
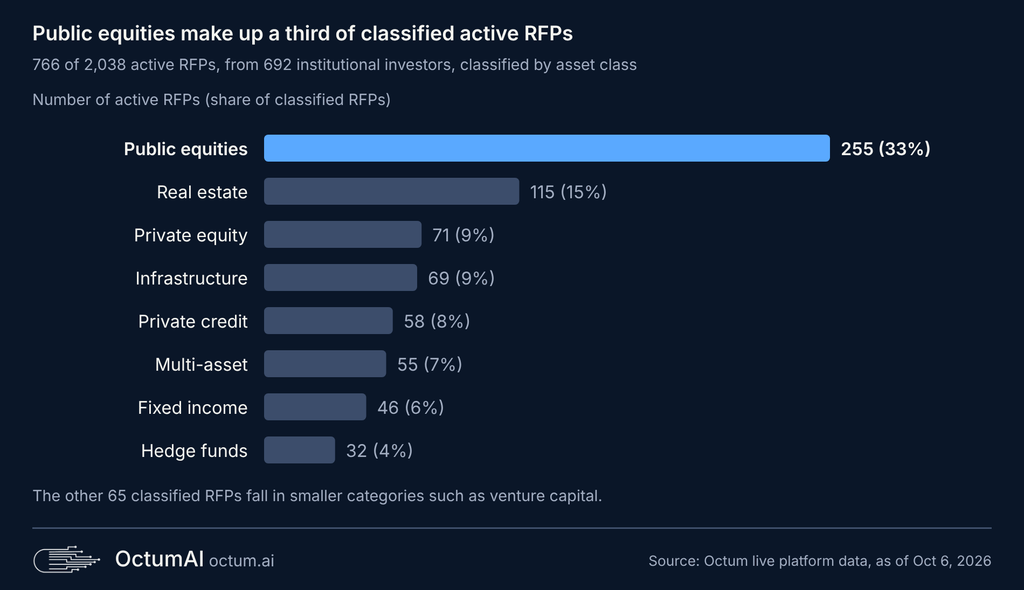
Build a monitoring routine.
- Save searches by asset class, region, investor type and mandate size, and review new RFPs at least weekly.
- Track each target allocator’s board calendar so you read agendas before the meetings that approve searches.
- Update consultant database profiles on a fixed quarterly schedule, the moment performance is final.
- Log every RFP you see, including those you pass on. The pattern tells you where demand is moving.
Go or no-go: how to decide which RFPs to answer
The fastest way to raise your win rate is to stop answering RFPs you cannot win. You do not have to answer every investment RFP you receive, and you should not. Ask three questions first: are you likely to win, can the team give the response the attention it needs, and is this a genuine opportunity or a lever the investor is using against its incumbent?
That last question matters. Fidelity notes that some nonprofits issue RFPs simply to benchmark their current provider (Fidelity). A benchmarking exercise can still be worth answering for the relationship, but price your effort accordingly.
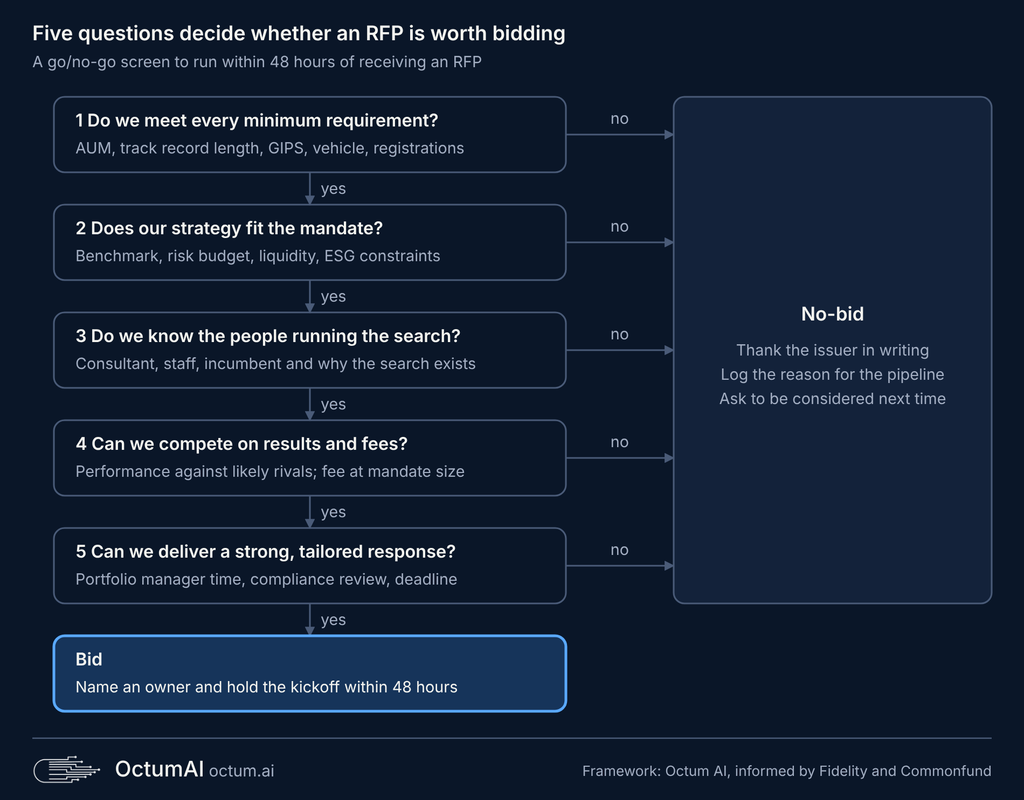
Run the screen in order. The first two questions are usually pass/fail; the last three are judgment calls you can score.
A simple go/no-go scorecard
Score each factor 0, 1 or 2, agree a threshold as a team, and record the score for every RFP so you can compare it with outcomes later.
| Factor | 2 points | 1 point | 0 points |
|---|---|---|---|
| Minimum requirements | Meet all with margin | Meet all, some narrowly | Miss any (stop here) |
| Strategy fit | Flagship strategy, exact benchmark | Adjacent strategy or benchmark | Would need a new product |
| Relationship | Known to consultant and staff | Known to one of them | Unknown to both |
| Why the search exists | Underperforming incumbent or new mandate | Scheduled review | Fee benchmarking only |
| Competitive position | Top-quartile results, fair fee | Middle of the pack | Weak results or uncompetitive fee |
| Capacity | Owner and PM time available | Tight but possible | Would weaken other bids |
| Strategic value | Flagship client or new segment | Normal fit | Low value, high service burden |
Use data, not instinct. Research the issuer before you score. Read its asset allocation, recent board minutes and consultant relationships; look up the investment team; and check which managers it already uses. Octum’s Ask Ora can surface an allocator’s decision makers and context in minutes, which turns the relationship and why-now questions from guesses into answers.
How to write a winning investment RFP response
Winning responses are built before the RFP arrives, then tailored hard once it does. The steps below follow the order a strong RFP team works in.
1. Build a governed content library
Answering the same question from scratch wastes your time and your portfolio managers’ time. Keep a central library of approved answers that can be searched, reused and improved. Make it work in practice:
- Store one approved answer per standard question: firm history, ownership, AUM, philosophy, process, risk management, ESG, cybersecurity, business continuity, conflicts of interest, key-person provisions.
- Tag each answer with an owner, a last-reviewed date and a compliance approval date.
- Refresh numbers (AUM, headcount, composite returns, client counts) every quarter, on a fixed calendar.
- Keep long and short versions. A 500-word philosophy answer and a 100-word version will both be needed.
- Make the library and your consultant database profiles say the same thing. Allocators compare them.
2. Run a kickoff within 48 hours
Read the whole document, including the instructions, minimum requirements, evaluation criteria and form requirements. Then hold a short kickoff with the sales lead, RFP writer, portfolio manager, compliance and operations. Agree on:
- The win theme: two or three reasons this allocator should hire you, in their language.
- A question-by-question owner matrix with internal deadlines that end two to three days before the real one.
- Questions to submit during the Q&A window. Clarifying questions show engagement, and answers are often shared with all bidders.
3. Answer the question that was asked
Evaluators score against a rubric. Make their job easy.
- Lead every answer with a direct response, then support it. If the question is yes/no, the first word is yes or no.
- Mirror the allocator’s terms and numbering. If they say “OCIO,” do not say “delegated solution.”
- Tailor to the mandate. Reference their Investment Policy Statement, benchmark, liquidity needs and constraints when they share them. Fidelity encourages issuers to share the IPS and holdings so managers can build customized portfolios (Fidelity).
- Respect page limits. Commonfund urges issuers to impose them precisely because unfocused responses bury the reader (Commonfund).
- Use tables for numbers, and footnote every data point with its as-of date.
4. Get performance presentation right
Performance is where proposals are disqualified most quickly.
- Present gross and net returns, benchmark comparisons, risk-adjusted metrics and attribution. These are the items Fidelity tells allocators to request.
- If you claim compliance with the GIPS standards, present a compliant GIPS report for the relevant composite. Only firms that manage assets on a discretionary basis and compete for business may claim compliance (CFA Institute).
- Never link simulated or model results to actual performance. The GIPS standards prohibit it.
- Follow the SEC Marketing Rule (Rule 206(4)-1). Gross performance must be accompanied by net performance. SEC staff FAQs issued in March 2025 added flexibility for extracted performance and portfolio characteristics (Vedder Price), and the FAQ page was updated again on January 15, 2026. Confirm with counsel which provisions apply to a given RFP response.
5. Treat public plans as a compliance exercise too
- Pay-to-play. SEC Rule 206(4)-5 bars advisers from receiving compensation from a government entity for two years after a covered associate makes a disqualifying political contribution. Check contributions before you bid.
- Placement agent disclosure. Many public plans require disclosure of third-party marketers and their fees.
- Required forms. Certifications, insurance evidence, MWBE forms and signed attestations are often pass/fail. Missing one can disqualify an otherwise strong response.
- Open records. Assume your response may become public. Mark proprietary sections as the RFP instructs.
6. Review like an evaluator
Evaluators notice the same red flags again and again: ignored instructions, internal contradictions, an off-brand tone, and technical or grammatical errors. Build a three-pass review:
- Compliance pass: every question answered, every form signed, every number footnoted, Marketing Rule and GIPS disclosures in place.
- Consistency pass: AUM, team names and returns match across the response, the DDQ and your database profiles.
- Persuasion pass: a senior reader checks that the win theme shows up in the executive summary, the process answer and the fee answer.
7. Submit early and follow up correctly
Upload a day early; portals fail at deadlines. Confirm receipt. Then respect the quiet period. Many public plans prohibit contact with board members and staff outside the official channel during a search.
How allocators score your response
Most committees score RFPs with a weighted scorecard agreed before responses arrive, so your answers are graded against criteria, not read as essays. Commonfund suggests a shared scorecard where each reviewer rates statements such as manager expertise with institutional nonprofits on a 1–10 scale, weighted by importance, and reuses it for finalist presentations (Commonfund).
The criteria themselves are fairly consistent across issuers. Weights vary by plan, so read the RFP’s stated evaluation criteria and mirror them.
| Criterion | What evaluators look for | How to score well |
|---|---|---|
| Organization | Ownership, stability, AUM trend, regulatory history, conflicts | Show stable ownership, disclose conflicts and how you manage them |
| People | Team depth, tenure, turnover, key-person risk, succession | Name the team that will run the mandate; show tenure and backups |
| Philosophy and process | A repeatable, clearly explained edge | Explain why it works, when it struggles and how you know |
| Performance | Gross and net returns, benchmark-relative results, risk-adjusted metrics, attribution, GIPS compliance | Show the full record, not a flattering window; explain bad periods |
| Risk management | Independent risk oversight, limits, liquidity and drawdown controls | Show the process and an example of it working |
| Fit with the mandate | Alignment with the IPS, benchmark, constraints and ESG policy | Tailor; reference their documents |
| Client service and reporting | Service model, reporting frequency, references from similar clients | Offer sample reports and comparable references |
| Fees | Level, structure and transparency; total cost | Answer in their fee table format; show the math at their mandate size |
| Operations and compliance | Business continuity, cybersecurity, valuation, service providers | Current, consistent DDQ answers |
References matter. Fidelity advises allocators to request three references from clients of similar size or type, because current clients reveal what interviews do not, such as onboarding and day-to-day service (Fidelity). Prepare references in advance and brief them.
Winning the finals presentation. Endowments and foundations typically narrow the field to two or three finalists. To prepare:
- Bring the portfolio manager who will run the money, not just the sales team.
- Open with what you heard: their objectives, constraints and concerns, in their words.
- Answer the scorecard. If they weighted risk management heavily, spend real time on it.
- Address the incumbent’s strengths honestly and explain what changes if they hire you.
- Rehearse the hard questions: your worst year, recent departures, capacity and fee pressure.
- Follow up within 48 hours with answers to anything left open.
12 mistakes that sink investment RFP responses
Most lost RFPs fail on avoidable process errors, not on investment merit. Check every response against this list.
- Bidding on everything. Low-fit bids drain the team and lower the quality of your best bids.
- Missing a minimum requirement. AUM, track record length, composite size or GIPS compliance thresholds are usually pass/fail.
- Ignoring the consultant database. If the search screens Callan or Wilshire data and your profile is stale, you never reach the RFP.
- Boilerplate that ignores the mandate. Generic answers score low against a rubric built around the allocator’s IPS.
- Not answering the question. Burying the answer in paragraph three costs points.
- Inconsistent numbers. AUM or returns that differ between the RFP, DDQ and database profile raise doubts fast.
- Performance presentation errors. Gross without net, cherry-picked periods, or GIPS claims without a compliant report.
- Exceeding page limits or ignoring format rules. Some issuers stop reading at the limit.
- Unsigned forms and missing attachments. Certifications, insurance evidence and Form ADV are easy to forget and hard to fix after the deadline.
- Skipping the Q&A window. You lose a free chance to clarify scope and show interest.
- Breaking the quiet period. Contacting trustees or staff outside official channels can disqualify you.
- No debrief after a loss. Ask for feedback and scores. Public plans often share evaluation results, and that data improves the next bid.
Pre-submission checklist
- Minimum requirements confirmed and evidenced
- Consultant database profiles updated this quarter
- Every question answered in the requested order and format
- Win theme appears in the executive summary, process and fee answers
- Performance shown gross and net, with benchmark, as-of dates and GIPS report where claimed
- Marketing Rule and GIPS disclosures reviewed by compliance
- Pay-to-play contribution check completed for public plans
- Fee proposal in the issuer’s format, calculated at the mandate size
- All forms signed; Form ADV, insurance and references attached
- Numbers consistent across RFP, DDQ and database profiles
- Page limits respected; file names follow instructions
- Submitted at least 24 hours early; receipt confirmed
Technology and AI in the investment RFP workflow
The RFP stack has split into two jobs: finding and qualifying opportunities, and producing responses. Most firms have invested in the second and still run the first on email alerts and spreadsheets.
The volume problem is real. In Cerulli’s survey, 91% of asset managers said their teams struggled to meet RFP and DDQ deadlines, even after doubling RFP staff over three years (Institutional Investor).
| Job | What good looks like | Tool category |
|---|---|---|
| Find opportunities | Every relevant search, across public portals, consultants and private allocators, in one feed | RFP trackers and investor intelligence (e.g., Octum) |
| Qualify and prioritize | Fit, decision makers, consultant and incumbent known before go/no-go | Investor and people intelligence (e.g., Ora) |
| Stay visible to consultants | Complete, consistent, quarterly-updated profiles | Consultant databases (e.g., CallanDNA, Wilshire Compass) |
| Produce responses | Governed content library, SME workflow, compliance approval | RFP response software. Octum (enterprise offering). |
| Learn | Win/loss reasons and scores feed the next go/no-go | CRM plus pipeline tracking |
Where AI helps, and where it does not. AI drafting tools speed up first drafts from your content library. They do not fix stale numbers, weak positioning or a bid you should not have made. Use AI to search, summarize and draft; keep humans accountable for performance figures, compliance language and the win theme.
Where Octum fits
Octum is an investment intelligence platform that tracks institutional RFPs and the people behind them. It helps business development teams at the top of the funnel: knowing which searches exist, who runs them and whether to pursue them.
- Active RFP tracking. As of October 6, 2026, Octum tracked 2,038 active RFPs from 692 institutional investors, across public equities, real estate, private equity, infrastructure, private credit, multi-asset, fixed income, hedge funds and venture capital.
- RFP management. Structured pipeline tracking, proposal management and automated matching of RFPs to your strategies.
- Ask Ora. Octum’s research engine answers plain-English questions about investors, fund managers and entities. For example, ask Ora to find the investment team at a pension plan, compare managers for a mandate, or draft outreach to decision makers (Ora).
- People and investor intelligence. Profiles of executives and board members, career paths and relationship mapping, plus 13F filing analysis for investor discovery.
- Signals and news. Curated financial news and regulatory and market signals that often precede a search.
Membership is a first month free, then $19 a month (octum.ai). Read how Octum compares with incumbents in Octum vs. Traditional Investor Databases for Fundraisers. For select qualifying clients, Octum can provide additional services.
Investment RFP FAQ
What is an investment management RFP? A formal questionnaire an institutional investor sends to several asset managers so it can compare them on the same criteria and hire one for a defined mandate.
What is the difference between an RFP and an RFI? An RFI is a short pre-screen of roughly 10–20 high-level questions sent to a broad group. An RFP is the detailed, scored document sent to a shortlist, often about five firms.
What is the difference between an RFP and a DDQ? An RFP asks why the allocator should hire you for a specific mandate. A DDQ checks whether your firm, fund and operations meet diligence standards. DDQs often follow industry templates such as the ILPA DDQ 2.0 or the AIMA DDQ.
How long do managers have to respond to an investment RFP? Endowments and foundations typically allow three to four weeks. Public plans set dates in the solicitation, and deadlines are usually firm.
How many managers receive an RFP? Nonprofits often send RFPs to 5–10 firms and interview 2–3 finalists. Public plans that must post searches publicly can receive dozens of responses.
How often do institutions issue RFPs for existing mandates? Recommendations range from every four years to every five to seven years, plus ad hoc searches after underperformance, team changes or contract expiration.
Do I need GIPS compliance to win institutional RFPs? It is not legally required, but many RFPs ask for it and some make it a minimum requirement. If you claim compliance, you must meet all applicable requirements and provide a GIPS report.
How do I find investment RFPs? Monitor public pension and municipal procurement portals, keep consultant database profiles current, follow industry trade press, and use an RFP tracker such as Octum to see searches across asset classes in one place.
What is a consultant database and why does it matter? Investment consultants screen managers using databases such as CallanDNA and Wilshire Compass. Many public searches require managers to enter data there before the consultant reports eligible firms.
Should we respond to every RFP we receive? No. Use a go/no-go framework. Bidding selectively improves win rates and frees time to tailor the bids that matter.
What is the pay-to-play rule? SEC Rule 206(4)-5 bars investment advisers from receiving compensation from a government entity for two years after certain political contributions by the firm or its covered associates.
The bottom line
Investment RFPs reward asset managers who see the search early, bid selectively and answer exactly what the allocator asked. The writing matters, but most wins are decided by preparation: a current content library, consistent database profiles, a disciplined go/no-go and a relationship with the people running the search.
Start with the pipeline. Join Octum to see thousands of active institutional RFPs across asset classes, research the investors and decision makers behind them with Ora, and track your pursuits in one place. Your first month is free.
Sources and further reading
Guides referenced in this article
- Fidelity Institutional: The layman’s guide to requests for proposals (RFPs)
- Commonfund: Top Ten Tips for Better OCIO RFPs and Is It Time to Issue an Investment Manager RFP for Your Nonprofit?
Industry data
- Institutional Investor / Cerulli: Asset Managers Say They’re Drowning in RFPs
- Octum: live platform data (as of October 6, 2026)
Standards, templates and rules
- CFA Institute: GIPS standards and 2020 GIPS Standards for Firms (PDF)
- ILPA: Due Diligence Questionnaire 2.0
- AIMA: Illustrative DDQ for investment managers
- SEC: Marketing Rule FAQ, Rule 206(4)-5 pay-to-play guide, Investment Adviser Public Disclosure (Form ADV)
- U.S. Department of Labor: Meeting Your Fiduciary Responsibilities
Sample RFPs and templates
- Indiana Public Retirement System: RFP 26-05 Global Public Equity Management (PDF) and the INPRS procurement page
- NYC Comptroller: Notice of Search for Equity Index Investment Management Products and Services
- NYC BERS: Investment consulting services RFP 2024-003
- State of Delaware: Endowment manager RFP
- New Jersey Turnpike Authority: Financial, investment and swap advisory RFP
- CalPERS: Investment Proposal Submission
This article is educational and is not legal, compliance or investment advice. Confirm regulatory requirements with your compliance team and counsel.